Sobha Amara EMI calculator
For the Sobha Amara 2 BHK at ₹1.61 Cr*, your EMI comes to about ₹1,03,760 a month. This assumes a 20-year loan at 7.5%. It also assumes a 20% down payment of about ₹32.2 lakh and a loan of ₹1.288 Cr. A 30-year tenure lowers the EMI to about ₹90,059, but you pay far more interest overall. Until possession in December 2029, you usually pay only pre-EMI interest on the amount released so far.
Use the tables below to estimate your EMI for any loan amount, rate and tenure. Then confirm the final figures with your bank once SOBHA shares the launch cost sheet.
*Indicative pricing, subject to change and developer confirmation.
Sobha Amara 2 BHK EMI by Tenure
These figures use a loan of ₹1.288 Cr at 7.5% interest.
| Tenure | Monthly EMI | Total Interest Paid |
|---|---|---|
| 15 years | ₹1,19,399 | ₹86.1 lakh |
| 20 years | ₹1,03,760 | ₹1.2 Cr |
| 25 years | ₹95,182 | ₹1.57 Cr |
| 30 years | ₹90,059 | ₹1.95 Cr |
A longer tenure eases your monthly budget, but nearly doubles the interest you pay. Many buyers choose 20 to 25 years and prepay when their income rises.
EMI Table for Common Loan Amounts
These figures use a 20-year tenure at three rates. Most banks price home loans in this range in October 2026, depending on your profile.
| Loan Amount | At 7.25% | At 7.75% | At 8.5% |
|---|---|---|---|
| ₹1 Cr | ₹79,038 | ₹82,095 | ₹86,782 |
| ₹1.288 Cr | ₹1,01,800 | ₹1,05,738 | ₹1,11,776 |
| ₹1.5 Cr | ₹1,18,556 | ₹1,23,142 | ₹1,30,173 |
| ₹2 Cr | ₹1,58,075 | ₹1,64,190 | ₹1,73,565 |
For the 3 BHK and 4 BHK homes, SOBHA shares prices on request. Pick the loan amount closest to your quote and read across.
How to Calculate Your EMI
Banks use one standard formula to work out a home loan EMI.
EMI = P × r × (1 + r)^n ÷ [(1 + r)^n − 1]
In this formula:
- P is your loan amount.
- r is the monthly interest rate, or the yearly rate divided by 12 and then by 100.
- n is the number of monthly payments, or years multiplied by 12.
For example, at 7.5% a year, r equals 0.00625. Over 20 years, n equals 240. Put these into the formula with your loan amount to get your EMI.
Pre-EMI During Construction
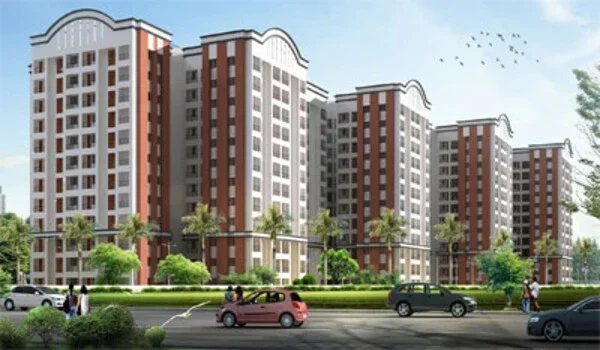
Sobha Amara is under construction, with possession expected in December 2029. On a construction-linked plan, your bank releases the loan in stages. Until the full loan goes out, you pay only interest on the amount released so far. This is called pre-EMI.
For example, if the bank has released ₹40 lakh at 7.5%, your monthly pre-EMI is about ₹25,000. This rises as the bank releases more money. Your full EMI starts once the bank disburses the whole loan.
Income You Need to Qualify
Banks usually keep your total EMIs within 40% to 50% of your take-home pay. Here is a rough guide for the 2 BHK loan.
| Monthly EMI | Take-Home Pay Needed at 50% | Take-Home Pay Needed at 40% |
|---|---|---|
| ₹1,03,760 (20 years) | About ₹2.08 lakh | About ₹2.6 lakh |
| ₹90,059 (30 years) | About ₹1.8 lakh | About ₹2.25 lakh |
A co-applicant, such as a working spouse, can raise your eligibility. Existing loans, such as a car loan, will lower it.
Ways to Lower Your EMI
- Make a larger down payment, so you borrow less.
- Add an earning co-applicant to qualify for a better rate.
- Keep your credit score above 750 before you apply.
- Compare offers from at least three lenders.
- Prepay part of the loan whenever you get a bonus.
Tax Benefits on Your Home Loan
Under the old tax regime, you can claim up to ₹1.5 lakh a year on principal under 80C. You can also claim up to ₹2 lakh a year on interest under 24(b) for your own home. Interest paid during construction counts too, spread over five years after possession. The new tax regime does not allow these deductions for a self-occupied home.
Should You Choose a Fixed or Floating Rate?
Most Indian home loans use a floating rate linked to the RBI repo rate. When the RBI raises the repo rate, your EMI or tenure goes up. When it cuts the rate, your cost comes down. The RBI has held the repo rate at 5.25% for its last four reviews. Its next decision comes on 7 October 2026. Many economists expect a small rise, so build some room into your budget for a higher EMI.
A fixed rate keeps your EMI steady, but banks usually price it higher than floating loans. Most fixed loans also switch to floating after a few years. For a long loan, a floating rate with regular prepayments usually costs less overall.
When You Can Apply for a Sobha Amara Loan
Banks lend only after a project gets its RERA number and passes their own approval. Sobha Amara's RERA registration is in progress, with the launch expected in November 2026. Get a loan eligibility check now, so you can move fast once lenders approve the project.
FAQs
On a ₹1.288 Cr loan at 7.5% over 20 years, the EMI is about ₹1,03,760 a month. This assumes a 20% down payment on ₹1.61 Cr*.
Banks usually fund 75% to 80% of the cost on large loans. For the 2 BHK, plan for at least ₹32.2 lakh plus taxes and charges.
Pre-EMI is the interest you pay on the loan amount released so far. Your full EMI starts after the bank releases the whole loan.
For a 20-year loan, you need a take-home pay of about ₹2.08 lakh to ₹2.6 lakh a month. A co-applicant can lower this.
SOBHA will share the list of approved lenders after RERA registration. Ask the sales team at launch.
Yes, the old regime lets you claim ₹1.5 lakh on principal and ₹2 lakh on interest a year.