NRI guide to buying property in Hyderabad
NRIs and OCI cardholders can buy residential and commercial property in Hyderabad without any approval from the RBI. You must pay through an NRE, NRO or FCNR account, and never in foreign currency cash. You cannot buy agricultural land, plantation property or farmhouses. Most banks lend NRIs up to 75% to 80% of the property value. You pay the same 7.5% Telangana stamp duty and 5% GST on new homes as resident buyers.
This guide covers the legal rules, payment routes, loans, taxes and the step-by-step process. It also explains why Hyderabad's western corridor draws so many NRI buyers today.
What NRIs Can and Cannot Buy in India
| Property Type | Allowed for NRIs and OCIs |
|---|---|
| Apartments, villas and independent houses | Yes, no limit on number |
| Commercial property such as offices and shops | Yes |
| Under-construction homes | Yes |
| Agricultural land | No |
| Plantation property | No |
| Farmhouses | No |
You can inherit agricultural land, but you cannot buy it. If you hold such land, speak to a lawyer about the rules for holding or selling it.
How NRIs Can Pay for Property
Foreign exchange rules allow only these ways to pay:
- Money sent from abroad through normal banking channels.
- Funds from your NRE account, which are fully repatriable.
- Funds from your NRO account, which carry repatriation limits.
- Funds from your FCNR account, converted to rupees.
- A home loan from an Indian bank or housing finance company.
You cannot pay in foreign cash, by travellers' cheques or in foreign currency straight to the seller.
Home Loans for NRIs
Indian banks and housing finance firms lend to NRIs on much the same terms as residents.
| Loan Factor | Typical NRI Terms |
|---|---|
| Loan amount | Up to 75% of value for loans above ₹75 lakh |
| Tenure | Usually 15 to 20 years |
| Interest rate | Often 0.25% to 0.5% above resident rates |
| Repayment | From NRE, NRO or FCNR accounts only |
| Co-applicant | Often a resident family member |
You need proof of income abroad, a valid passport, a visa or OCI card, PAN and bank statements.
Taxes and Charges NRIs Pay in Hyderabad
| Charge | Rate |
|---|---|
| Telangana stamp duty | 5.5% |
| Transfer duty | 1.5% |
| Registration fee | 0.5% |
| GST on under-construction homes above ₹45 lakh | 5% |
| TDS when buying from a resident seller, ₹50 lakh or more | 1% under Section 194-IA |
The 1% TDS also applies when you buy a new flat from a builder. You deduct it from the payment and deposit it using Form 26QB with your PAN.
Repatriation Rules When You Sell
If you paid with NRE, FCNR or money sent from abroad, you can send the original amount back. This applies to up to two residential properties. Money from an NRO account can go back abroad up to USD 1 million each financial year. You will need Form 15CA and a CA certificate in Form 15CB.
Tax When an NRI Sells Property
Since the 2024 Budget, long-term gains on property held over 24 months face 12.5% tax without indexation. Short-term gains face tax at your slab rate. The buyer must deduct TDS on the full sale value, not just the gain. You can apply under Section 197 for a lower TDS certificate if your actual tax is smaller. India's tax treaties with your country of residence may also reduce double taxation.
Step-by-Step Process for NRIs Buying in Hyderabad
- Open or update your NRE or NRO account with an Indian bank.
- Get your PAN card, if you do not already have one.
- Shortlist RERA-registered projects on the Telangana RERA portal.
- Get a loan eligibility check from two or three lenders.
- Pay the booking amount through your NRE or NRO account.
- Sign the agreement for sale, in person or through a registered power of attorney.
- Pay stage-wise as per the payment plan and track progress on RERA.
- Register the sale deed and pay 7.5% stamp duty and fees.
Power of Attorney for NRI Buyers
Most NRIs give a power of attorney to a trusted relative to handle registration in India. Sign it at the Indian embassy or consulate, or get it apostilled in your country. Keep the POA specific to one property and one purpose, with a clear end date. Never give a broad POA to a broker or agent.
Why NRIs Choose Hyderabad's Western Corridor
Hyderabad recorded the strongest yearly growth in housing sales among India's top seven cities in Q3 2026. Anarock data shows the city sold about 12,970 homes, up 15% over the same quarter in 2025. The western belt of the Financial District, Kokapet and Gachibowli drives much of this demand. Many NRIs buy here for rental income from IT tenants or for a future return home.
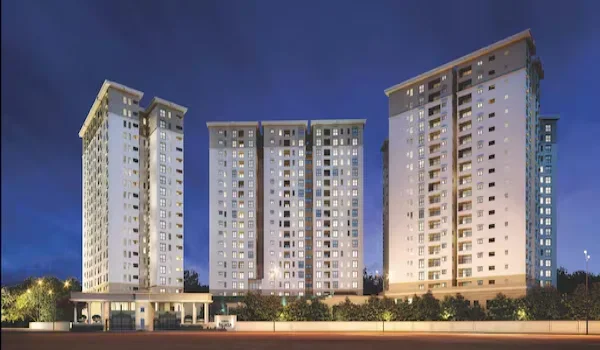
New branded high-rises along this belt now suit NRI buyers well. Take Sobha Amara at Kismatpur, about 4 km from the Financial District. Its builder, SOBHA Limited, trades on the BSE and NSE. The 2 BHK starts from an indicative ₹1.61 Cr*, and possession is due in December 2029. As with any project, wait for the TG RERA number before you remit any money.
*Indicative pricing, subject to change and developer confirmation.
FAQs
Yes, NRIs and OCI cardholders can buy residential and commercial property without RBI approval. They cannot buy agricultural land, plantations or farmhouses.
No, NRIs do not need RBI permission to buy residential or commercial property in India.
Yes, Indian banks lend NRIs up to about 75% of the value on large loans. Repayment must come from an NRE, NRO or FCNR account.
NRIs pay the same 7.5% as residents. That covers 5.5% stamp duty, 1.5% transfer duty and 0.5% registration.
Yes, through a registered power of attorney given to a trusted relative. Sign it at an Indian consulate or get it apostilled abroad.
Yes, NRIs can repatriate the original purchase amount for up to two homes bought with foreign funds. NRO funds allow up to USD 1 million a year.